JuliaActuary
Packages
Docs
Learn
Examples
Community
Benchmarks
Blog
Book
All Posts
Tutorials, articles, and updates from JuliaActuary.
Categories
All
(30)
actuaryutilities
(5)
alm
(1)
assets
(1)
autodiff
(3)
bayesian
(4)
benchmark
(3)
blog
(10)
code
(10)
contributing
(1)
credibility
(1)
dataframes
(3)
design
(1)
diffeq
(1)
experience-analysis
(6)
exposures
(2)
finance
(1)
financemodels
(3)
industry
(3)
market
(1)
modeling
(13)
mortalitytables
(5)
python
(1)
r
(1)
scenario-generator
(2)
statistics
(8)
survival
(1)
tutorial
(11)
yieldcurves
(1)
Interactive AAA Economic Scenario Generator
modeling
scenario-generator
Scroll down below the sample video to see how to run it.
Replicating the AAA equtity generator
modeling
scenario-generator
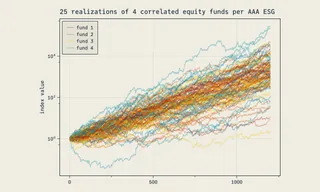
This notebook replicates the model and parameters for the real world equity generator described in this AAA 2005 reference paper.
Autodifferentiation and Asset Liability Management (AAD & ALM)
modeling
autodiff
alm
Asset liability modeling requires computing derivatives of portfolio values with respect to yield curve changes. Traditional approaches use finite difference methods or…
Bayesian vs Limited Fluctuation Experience Analysis
modeling
statistics
experience-analysis
bayesian
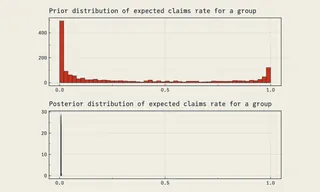
Alternate title: Why actuaries should cease to care about the number 1082.
Bayesian Markov-Chain-Monte-Carlo and Claims Data
mortalitytables
exposures
experience-analysis
dataframes
tutorial
statistics
bayesian
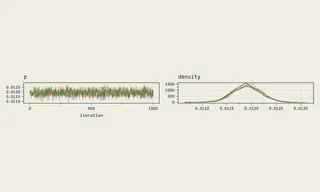
The problem of interest is to look at mortality rates, which are given in terms of exposures (whether or not a life experienced a death in a given year).
Interactive Cashflow Analysis with ActuaryUtilities.jl
actuaryutilities
financemodels
assets
Scroll down below the sample video to see how to run it.
Credibility When Claims Are Scarce
Comparing limited fluctuation, Bühlmann–Straub, and hierarchical Bayes on sparse mortality data
statistics
experience-analysis
bayesian
credibility
modeling
Your best customers are the ones you know least about.
Exposure Calculation with ExperienceAnalysis.jl
mortalitytables
exposures
experience-analysis
dataframes
tutorial
In this tutorial, we will walk through how to calculate exposures using the ExperienceAnalysis.jl package.
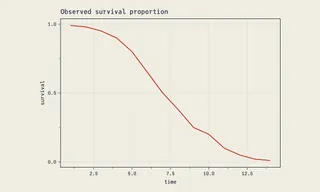
Fitting survival data with MortalityTables.jl
survival
tutorial
This tutorial is via PharmCat on Github (this link has similar code with comments in Russian and English).
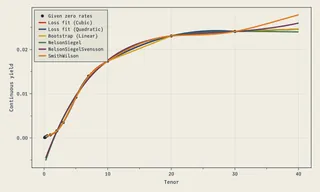
Fitting Rate Data to Yield Curves
market
yieldcurves
financemodels
tutorial
Given rates and maturities, we can fit the yield curves with different techniques.
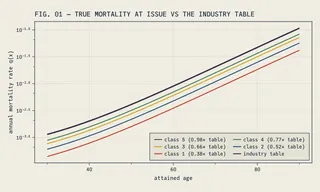
Interactive Mortality Comparison Tool
experience-analysis
mortalitytables
Scroll down below the sample video to see how to run it.
Using MortaltiyTables.jl with DataFrames
mortalitytables
dataframes
tutorial
MortalityTables.jl stores the rates in a very efficient manner as a collection of vectors indexed by attained age.
Nested Projection Mechanics
modeling
benchmark
actuaryutilities
tutorial
A simple example of how one could define a nested projection system. Includes the following examples: - Outer loop policy projections only - Outer + Inner loop policy…
How Much Capital Does Model Error Cost?
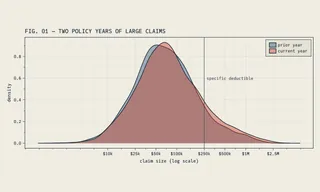
Optimal transport for actuaries, continued: put a dollar budget on how wrong the loss model could be, and price the exact worst case that budget allows
actuaryutilities
statistics
modeling
tutorial
Every capital number comes out of a model. Not out of the book of business — out of a model of the book. Everyone in the room knows the model is wrong; the argument is only…
How Far Did the Book Move?
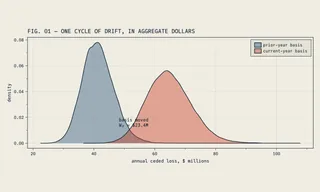
Optimal transport for actuaries: sort the claims, measure the drift in dollars, and be honest about how wrong the model is
actuaryutilities
statistics
modeling
tutorial
Somewhere right now, an actuary is in a meeting about whether the book of business has changed. There is a slide with two means on it. Someone remembers a bad claim from…
Poisson approximation to Binomial
modeling
statistics
experience-analysis
This notebook explores using the Poissson approximation to the Binomial. This can be useful for a number of reasons:
Universal Life Policy Account Mechanics as a Differential Equation
modeling
diffeq
mortalitytables
actuaryutilities
tutorial
This demonstrates an example of defining an universal life policy value roll like a discrete differential equation.
Stochastic claims projections demo
modeling
benchmark
tutorial
Define a datatype. Not strictly necessary, but will make extending the program with more functions easier.
US Treasury Comparison Tool
modeling
financemodels
tutorial
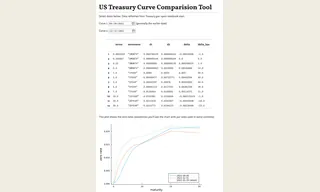
The screenshot above shows a Pluto.jl notebook where you can select a pair of dates and find the change in the treasury curve’s zero rates.
FinanceModels 7, ActuaryUtilities 6, MortalityTables 3, FinanceCore 3 and LifeContingencies 3
code
blog
Five major JuliaActuary releases improve curve calibration, interest-rate risk, life-contingent valuation and mortality calculations. They add sensitivities through…
Oct 11, 2026
Alec Loudenback
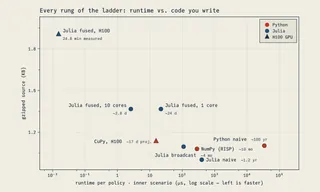
Nested Stochastic Projections: Python vs. Julia
Reworking the SOA’s open-source VA valuation, where the fastest implementation turns out to be the one that looks like the specification
modeling
benchmark
code
autodiff
blog
“The computational structure of a NSM has been the elephant in the room over the past few years. While we were all busy talking about the different approximation methods to…
Jul 31, 2026
Alec Loudenback
Cassette Futurism: a Makie theme preview
design
code
A draft Makie theme exploring a
cassette futurism
/
NASA-punk
look for JuliaActuary plots: Apollo-era flight-plan manila, navy plotter-pen ink, instrument-panel accent…
May 24, 2026
Alec Loudenback
JuliaActuary and QuantLib: cashflows, curves and sensitivities
blog
code
autodiff
finance
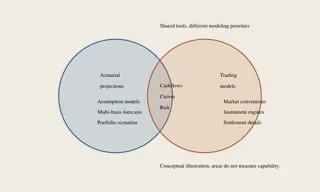
Actuarial projections and trading models share cashflows, curves and risk measures, but put different demands on them. A multi-basis forecast of 100,000 annuity contracts…
May 21, 2026
Alec Loudenback
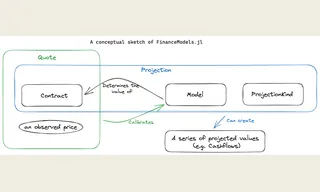
FinanceModels.jl - Evolving the JuliaActuary Ecosystem
code
blog
This August 2023 article describes the original FinanceModels 4 interface. Its extension hooks, projection examples and non-linear bootstrap calls are historical. For…
Aug 19, 2023
Alec Loudenback
Modern Bayesian Statistics for Actuaries
code
statistics
blog
One of the first probabilistic theorems everyone learns is Bayes’ Theorem, but that theorem is conspicuously absent from most applications and practice. The reason for this…
Jul 13, 2023
Alec Loudenback
JuliaActuary and Hacktoberfest 2022
code
contributing
blog
Hacktoberfest is DigitalOcean’s annual event that encourages people to contribute to open source throughout October.
Sep 24, 2022
Getting Started with Julia for Actuaries
industry
blog
statistics
bayesian
The previously published article titled Julia for Actuaries gave a longer introduction to why Julia works so well in actuarial workflows. In summary: Julia’s attributes are…
Oct 24, 2021
Alec Loudenback and Dimitar Vanguelov
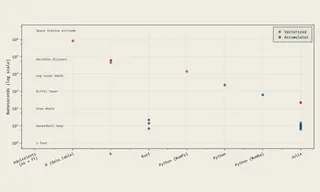
The Life Modeling Problem: A Comparison of Julia, Rust, Python, and R
code
blog
!! Note that this article is a draft
May 16, 2021
Alec Loudenback
Coding the Future
code
industry
blog
“…the insurance business is perhaps the purest example of an ‘information-based’ industry - that is, an industry whose sole activity consists of gathering, processing, and…
Jul 9, 2020
Alec Loudenback
Julia for Actuaries
code
industry
r
python
blog
I have suggested that actuaries who are competent coders will differentiate both themselves and the companies they work for. Coding ability will be useful no matter what…
Jul 9, 2020
Alec Loudenback
No matching items